
Homebody: Better Renting
- Rating
- 4.6
- Downloads
- 50.00K
- Content Rating
- Everyone
Homebody: Better Renting - Screenshots
Pros
- Helps renters organize maintenance requests and landlord communications.
- Makes it easier to keep a record of issues with photos and notes.
- Useful reminders can help track inspections
- repairs
- and rental deadlines.
- Simple interface is approachable for users with little property-management experience.
- Can improve communication clarity by keeping rental details in one place.
Cons
- Some features may depend on landlord or property-manager participation.
- Availability and usefulness can vary by country and local rental regulations.
- Users may need to enter considerable property information before seeing benefits.
- Cloud-based rental records may raise privacy concerns for some tenants.
- The app cannot guarantee faster repairs or resolve disputes with landlords.
Homebody: Better Renting - Description
- App Name
- Homebody: Better Renting
- Package Name
- com.homebody
- Developer
- Entrata, Inc
- Category
- Lifestyle
- Last Updated
- Oct 9, 2023
- Version
- 2.0.23
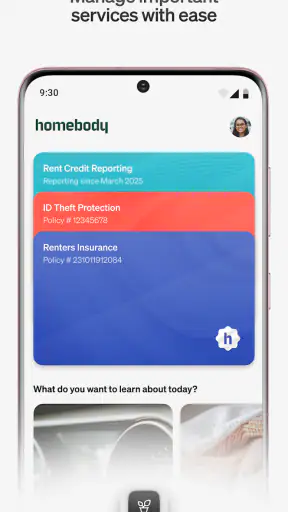
Renting usually involves several separate tasks: protecting your belongings, keeping track of housing costs, and making sure your rent history does not disappear into a credit file. Homebody: Better Renting brings those concerns into one lifestyle app from Entrata, Inc., which makes it worth considering if you want a simpler way to manage the financial side of renting. I spent time looking at it as a practical renter’s tool rather than treating it like a general apartment search service, and that distinction matters.
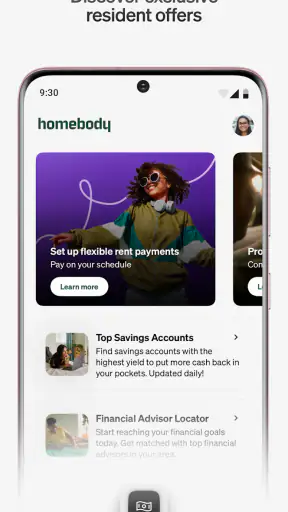
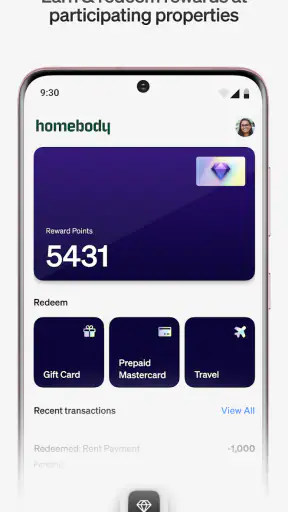
The app is free, aimed at everyone, and available for devices running Android or iOS 10 and later. It belongs in the lifestyle category, but its useful value is more specific: it connects renters with insurance, potential savings, and credit-building tools. That combination is appealing, although it also means the app is most useful when those three areas match your situation. If you only need a basic insurance policy or a standalone credit-monitoring service, a more focused alternative may feel clearer.
What I looked for before recommending it
My first decision criterion was whether the app could reduce the number of separate renter-related chores without making the process confusing. A renter may already be dealing with a lease portal, an insurance provider, a bank, and a credit service. Putting additional tools in one place sounds convenient, but convenience only counts if the app helps you understand what you are doing rather than simply adding another account to maintain.
The second criterion was usefulness over time. Insurance is something you arrange and revisit, while credit building depends on consistent behavior and patience. I therefore looked at Homebody as an app that could support an ongoing renting routine, not as a one-time download. The important question is whether it gives you a reason to return when you are not moving, renewing a lease, or dealing with a problem.
I also considered how well it serves different types of renters. Someone renting their first apartment may value guidance and a single starting point. An experienced renter with established insurance and a carefully managed credit profile may see less benefit. That difference is central to my verdict: Homebody is not automatically better than every specialized service; it is better suited to people who want connected renter-focused tools.
The public response is encouraging, with a 4.6 average from over 500 ratings and more than 50,000 installs. Those figures suggest that the app has found an audience, but they should not replace your own judgment. A strong rating cannot tell you whether its insurance options fit your property, whether its credit-related tools match your goals, or whether you will actually use the app after the initial setup.
A useful starting point for new renters
Homebody makes the most sense when you are trying to organize the less visible responsibilities of renting. A lease tells you how much rent is due, but it may not help you think through protection for personal belongings or the long-term effect of consistent housing payments. The app’s focus on insurance, saving money, and building credit gives a first-time renter a more complete checklist than a simple rent-payment screen.
For a new renter, I would use it early in the moving process. Before signing up for anything, gather the information you already have about your lease, your household, and your current financial arrangements. This makes it easier to compare what Homebody offers with what you already use. The practical advantage is not merely having another dashboard; it is being able to identify gaps before they become expensive or stressful.
One non-obvious benefit is that the app can encourage you to treat renting as part of your broader financial routine. Many people think of rent as an unavoidable monthly bill and do not connect it with credit-building opportunities. Homebody’s positioning prompts a different question: can your regular housing behavior contribute to a stronger financial profile? That is a useful mindset shift, even if the actual results depend on eligibility, consistency, and the details of your rental arrangement.
How the three-part focus works in everyday life
Imagine you have just moved into a new apartment. You are unpacking, updating your address, and trying to remember which services must be arranged immediately. Instead of opening separate apps at random, you can use Homebody as a checklist for the renter-specific areas that are easiest to overlook. I would start with insurance, then review the savings angle, and finally examine the credit-building option as a longer-term task.
That order is deliberate. Protection from a loss is generally a more immediate concern than improving a credit profile, while savings depend on understanding the actual offer rather than assuming every suggestion will apply to you. Treating the app as a sequence of decisions, rather than tapping through every screen quickly, makes it more useful.
A second practical workflow is to revisit the app around a lease renewal. Your household may have changed, your belongings may be worth more, or your financial priorities may be different. Reviewing the app at that point can help you decide whether your current arrangements still make sense. I would not change insurance or financial services automatically, but I would use the renewal date as a prompt to compare and reassess.
Where it is stronger than scattered alternatives
The clearest strength is the renter-centered combination. A traditional insurance app may do a better job of focusing exclusively on coverage. A credit-focused app may offer a deeper view of credit activity. A banking app may be more familiar for tracking money. Homebody’s advantage is that it starts with the renting relationship and connects those concerns around it.
That makes it particularly useful for people who dislike managing several unrelated services. The app can act as a central reminder of the financial decisions tied to your home, even when each decision still requires careful attention. I appreciate that approach because renters often receive plenty of information about monthly rent but less help connecting rent, protection, and financial progress.
Another strength is accessibility. The app is free, carries an Everyone content rating, and supports older operating systems from version 10 onward. That lowers the barrier to trying it, especially if you do not want to commit money before understanding whether a renter-focused tool fits your routine. Free access does not guarantee that every related service is free or suitable, so I would still read each offer carefully before accepting it.
The current version is 2.0.23, which indicates that the app has continued through version updates rather than remaining at its original release state. It first appeared on October 9, 2023. I would treat that history as a reason to keep the app updated, particularly for an application dealing with personal and financial information. Updating is a small habit, but it helps avoid judging an older build when the current experience may have changed.
Three ways to get more value from it
First, use Homebody before you need it. Downloading it during a stressful move can turn every screen into another task. Installing it earlier gives you time to compare its suggestions with your existing insurance and financial setup. This is especially valuable if you share a home, because you can decide in advance which renter responsibilities belong to you and which belong to someone else in the household.
Second, separate recommendations from decisions. If the app presents a way to save money or build credit, do not treat the presence of that option as proof that it is automatically the best choice. Write down what you already pay, what you already have, and what outcome you want. Then compare the app’s path with your current arrangement. This prevents the common mistake of switching simply because a new service appears more convenient.
Third, make credit-building a measurement exercise rather than a quick experiment. Think about whether you can maintain the required behavior over time and whether your rental situation is compatible with the feature. The useful insight here is that credit progress is not something to judge after a few taps. Homebody may help you begin the process, but it cannot replace steady payments, sensible borrowing, and regular attention to your wider finances.
When another category may be a better fit
Homebody is less compelling if you already have a trusted insurance provider, a separate budgeting system, and a credit service that you understand well. In that situation, the app may duplicate tools rather than simplify them. A specialized alternative can be better when depth matters more than convenience. For example, someone comparing detailed insurance choices may prefer to work directly with an insurer or an independent comparison service, while someone focused on credit education may want a dedicated credit platform.
It may also be the wrong choice if you expect a full property-management app. Homebody’s identity is built around making renting financially easier, not around replacing every possible lease, maintenance, or building-communication tool. If your main need is submitting repair requests, checking building announcements, or communicating with a property manager, you should look for the service your housing provider actually uses. Homebody should complement that kind of portal, not be assumed to replace it.
Privacy-conscious renters should take a careful approach before connecting financial or housing information. I would read the permission requests and service terms, use a strong account password, and avoid entering information casually just to explore a screen. This is not a criticism unique to Homebody; it is a sensible rule for any app that touches insurance, rent, savings, or credit. The convenience of one place is valuable only if you are comfortable with the information required to use it.
There is also a trade-off for people who do not like bundled experiences. When insurance, savings, and credit appear together, the app can make renting feel more organized, but it can also blur the difference between separate financial decisions. I prefer to keep those decisions mentally distinct. Insurance protects against certain risks, savings reduce pressure on your budget, and credit-building serves a longer-term goal. Homebody is most effective when you use its connected structure without treating all three as the same kind of product.
What switching really involves
Trying Homebody is relatively easy because the app itself is free. The larger cost of switching comes from attention. You may need to review your current insurance, understand how a new savings opportunity affects your routine, and decide whether a credit-building feature fits your circumstances. That time is worthwhile only if the app replaces confusion with a clearer process.
I would not cancel existing services immediately after installing it. Keep your current arrangements active until you understand what Homebody offers and have confirmed that any replacement is appropriate. This is particularly important for insurance: a gap in coverage is far more serious than the inconvenience of maintaining two accounts temporarily. A cautious transition also lets you compare the real experience rather than relying on an initial impression.
For credit-related use, the switching cost is even more about expectations. If you are moving from a dedicated credit tool, you may miss detailed monitoring or educational material that Homebody does not aim to provide. If you are starting from nothing, the app may be a helpful entry point, but you still need to learn the underlying habits. I would choose Homebody for a simple starting workflow, not because I expect it to become my complete financial education system.
One realistic routine would be to check it when your rent cycle changes, when you renew a lease, or when your household circumstances change. I would avoid opening it compulsively every day unless it gives you a clear reason to do so. That approach keeps the app useful without turning it into another source of financial noise.
My recommendation for different renters
I recommend Homebody most strongly to renters who want one free place to begin organizing insurance, savings, and credit-building decisions. It is especially suitable for first-time renters, people who have recently moved, and anyone who suspects that their current housing routine is disconnected from their wider financial goals. The app’s focused combination is more useful than a generic lifestyle download because it addresses problems that are specific to renting.
I would be more cautious if you already have mature systems in place. Experienced renters with carefully selected insurance, established budgeting habits, and a preferred credit service may find that Homebody adds overlap. In that case, compare its convenience against the clarity of the tools you already trust. A dedicated alternative may be better when you need specialized detail, while Homebody is better when you need a renter-focused starting point.
My final view is positive, with sensible limits. Homebody does not remove the need to read terms, compare choices, or manage your money responsibly. What it does offer is a practical way to connect several renter concerns that are often handled separately. I would install it before a move or lease renewal, explore it methodically, and keep only the parts that genuinely improve my routine. For a free lifestyle app with a clear renting focus, that is a worthwhile proposition.
FAQ
What is Homebody: Better Renting?
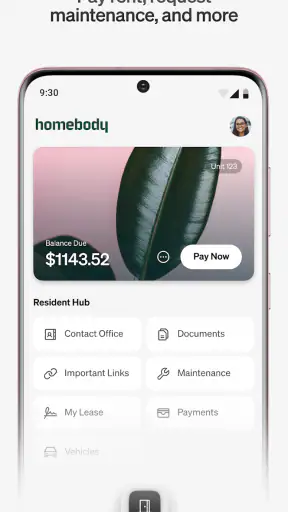
Homebody: Better Renting is a rental-focused app designed to help users manage and improve their renting experience. Depending on your location and account type, it may provide tools for organizing tenancy information, communicating with property managers, reporting maintenance issues, accessing important documents, and keeping track of rental-related tasks. Its usefulness can vary by landlord, letting agency, or housing provider integration.
Who can use Homebody: Better Renting?
The app is primarily intended for renters, tenants, and people managing a residential rental property through a participating landlord, letting agency, or housing organization. Some features may require an invitation, a registered tenancy, or verification of your rental details. Before downloading, check whether your property manager supports Homebody, because access and available functions may differ depending on the provider and your region.
What features does Homebody offer to renters?
Homebody is built around making everyday renting more organized and convenient. Common features may include viewing tenancy information, storing or accessing rental documents, sending messages, reporting repairs, receiving updates, and managing relevant requests from one place. The exact tools available can depend on the organization connected to your account, so not every user will necessarily see the same menus or services.
Is Homebody: Better Renting free to download and use?
The app may be available to download without an upfront charge, but the practical cost and access conditions can depend on your landlord, agency, or housing provider. Some services could be included as part of a rental management arrangement, while other optional features may have separate terms. Review the app-store listing, provider instructions, and privacy or subscription information before creating an account.
Is Homebody safe for storing rental and personal information?
Because a rental-management app can contain personal details, tenancy records, messages, and maintenance information, users should review its privacy policy and security practices before using it. Download Homebody only from an official app store, use a strong unique password, and keep your device updated. Avoid sharing login codes, and contact your property provider through an official channel if you notice suspicious activity.


